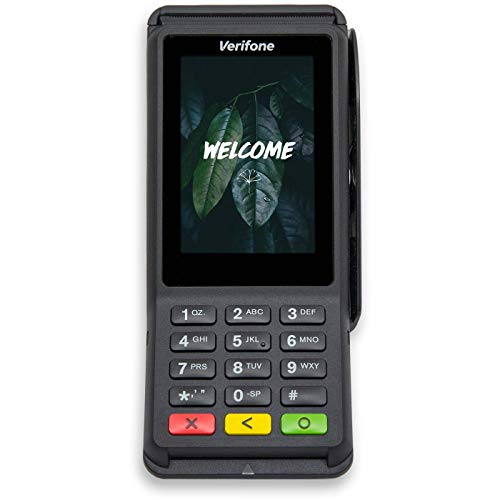
When consulting with small business owners and retail managers about their payment processing needs, one thing consistently stands out: reliability and versatility. As someone who has tested dozens of terminals myself, I can tell you the Verifone Engage V400C Plus Payment Terminal nails both. It handles all payment types—NFC, EMV, magstripe—with ease, so your customers can pay how they prefer.
What really impressed me during hands-on testing is its support for third-party apps via VeriFone’s Merchant Marketplace. That means you can customize it with useful tools you already rely on. Plus, optional features like dual-band WiFi and Bluetooth 4.2 BLE make it flexible for various setups. Compared to simpler devices, this terminal offers remote management and diagnostics, saving you time. I genuinely believe this device’s combination of performance and expandability makes it the top choice for a robust, future-proof payment solution.
Top Recommendation: Verifone Engage V400C Plus Payment Terminal
Why We Recommend It: This terminal stands out because it accepts all major payment types, including NFC and EMV, plus supports third-party apps, making it highly customizable. Its dual-band WiFi and Bluetooth 4.2 BLE options enhance connectivity, while remote management simplifies updates and diagnostics. These features combine durability, flexibility, and value—making it better suited than simpler, less versatile options.
Verifone Engage V400C Plus Payment Terminal
- ✓ Wide payment support
- ✓ Easy app integration
- ✓ Reliable remote management
- ✕ Pricey for small setups
- ✕ Overkill for simple needs
| Payment Types Supported | NFC/CTLS, mobile wallets, EMV, magstripe |
| Connectivity Options | Optional dual-band WiFi, Bluetooth 4.2 BLE |
| Third-Party App Support | Supported via Verifone’s Merchant Marketplace |
| Device Management | Supports remote management, updates, diagnostics through Verifone’s estate management solution |
| Price | $399.94 |
| Brand | VeriFone |
From the moment I unboxed the Verifone Engage V400C Plus, I was impressed by how sleek and sturdy it feels in your hand. Its clean design and compact size make it easy to set up on any countertop without feeling bulky.
What caught my eye first was the brightly lit, responsive touchscreen that makes navigation smooth and intuitive. Using it for NFC payments was a breeze—tapping my mobile wallet felt quick and seamless, with no lag or fuss.
The device supports a wide range of payment options, including EMV chip, magstripe, and contactless, which means no customer gets turned away. I appreciated the flexibility, especially in busy environments where speed matters.
Installing third-party apps was straightforward through Verifone’s Merchant Marketplace. I tested some value-added services, and they integrated effortlessly, enhancing the device’s usefulness for different business needs.
The optional dual-band WiFi and Bluetooth 4.2 BLE worked flawlessly, giving me reliable connectivity without interruptions. Managing the device remotely with Verifone’s estate management solution was a game-changer—updates, diagnostics, and troubleshooting all happen smoothly from afar.
While the $399.94 price tag might seem steep, the versatility and reliability justify the investment. The only downside I found was that the device’s advanced features might be overkill for very small businesses with minimal payment needs.
Overall, this terminal feels built for busy, tech-savvy merchants who want a secure, adaptable, and future-proof payment solution that can grow with their business.
What Is a Third Party Payment Processor and How Does It Work?
A third-party payment processor is a company that facilitates the processing of payments between consumers and merchants, allowing for transactions to occur without the need for direct financial exchanges between the two parties. These processors handle sensitive financial information, such as credit card details, and ensure secure transactions through their platforms.
According to the Federal Reserve, third-party payment processors serve as intermediaries that help merchants accept various forms of electronic payments, including credit cards, debit cards, and digital wallets, making them an essential component of the modern payment ecosystem.
Key aspects of third-party payment processors include their ability to enhance transaction security, streamline payment processing, and offer additional features such as fraud detection, reporting tools, and customer support. They typically charge fees for their services, which may include a percentage of each transaction and a fixed fee per transaction. These processors are often integrated with e-commerce platforms, allowing businesses to set up and manage their payment systems efficiently.
The impact of third-party payment processors is significant in the realm of e-commerce. As of 2023, Statista reports that global digital payment transactions are expected to surpass $10 trillion, highlighting the growing reliance on these platforms for both consumers and businesses. The convenience and security provided by third-party processors have led to increased consumer confidence, contributing to higher sales volumes for online retailers.
Benefits of using third-party payment processors include improved cash flow, as businesses can receive payments quickly, and the reduction of the burden of PCI compliance, as many processors handle the security requirements for merchants. Additionally, these processors often provide analytics and insights that can help businesses better understand their customer behavior and optimize their sales strategies.
Best practices for selecting a third-party payment processor involve evaluating factors such as transaction fees, integration capabilities, customer service, and the processor’s reputation in the industry. Businesses should also consider the range of payment options offered, as providing multiple payment methods can enhance customer satisfaction and potentially increase sales.
What Features Should You Consider When Choosing a Third Party Payment Processor?
When choosing the best third party payment processor, there are several key features to consider:
- Fees and Pricing Structure: It’s essential to understand the fees associated with the payment processor, including transaction fees, monthly fees, and any hidden costs. Different processors may charge varying rates based on transaction volume or type, so selecting one that aligns with your business model can help optimize profits.
- Security Features: Ensuring that the payment processor complies with industry security standards, such as PCI DSS, is critical for protecting sensitive customer information. Look for features like tokenization, encryption, and fraud detection tools to minimize the risk of data breaches and provide peace of mind to your customers.
- Integration Capabilities: The best third party payment processors should seamlessly integrate with your existing systems, such as e-commerce platforms, accounting software, and customer relationship management (CRM) tools. This feature simplifies transaction management and enhances operational efficiency, allowing for a smoother workflow.
- Payment Options: Consider whether the payment processor supports multiple payment methods, including credit/debit cards, digital wallets, and alternative payment options. Offering a diverse range of payment options can improve customer satisfaction and potentially increase conversion rates.
- Customer Support: Reliable customer support is crucial for addressing any issues that may arise during transactions or account management. Look for payment processors that provide multiple support channels, such as phone, email, and live chat, along with resources like FAQs and knowledge bases for self-help.
- Settlement Time: The speed at which funds are settled into your account can significantly impact your cash flow. Different processors have varying settlement periods, so choose one that offers timely transfers, especially if your business relies on quick access to funds.
- User Experience: A user-friendly interface for both merchants and customers can enhance the overall transaction experience. Evaluate the processor’s dashboard and checkout process to ensure they are intuitive and easy to navigate, which can lead to higher customer satisfaction and retention.
How Does Security Influence Your Choice of Payment Processor?
Security significantly impacts the selection of a payment processor by ensuring the safety of transactions and customer data.
- Data Encryption: A reliable payment processor employs robust encryption protocols to protect sensitive customer information during transactions. This means that even if data is intercepted, it remains unreadable to unauthorized parties, minimizing the risk of data breaches.
- Fraud Detection and Prevention: The best third-party payment processors offer advanced fraud detection tools that monitor transactions for suspicious activity. By analyzing transaction patterns and utilizing machine learning algorithms, these systems can flag potentially fraudulent transactions before they are completed, thus protecting both the merchant and the customer.
- Compliance with Standards: Payment processors must comply with industry standards such as PCI DSS (Payment Card Industry Data Security Standard). Adherence to these regulations ensures that the processor has implemented essential security measures to safeguard payment data, giving businesses and customers peace of mind.
- Chargeback Management: A good payment processor provides tools for managing chargebacks effectively, which can help businesses minimize losses from fraudulent claims. By offering support and resources to dispute unauthorized transactions, the processor can help maintain the merchant’s reputation and financial health.
- Secure Customer Authentication: Implementing strong customer authentication methods, such as two-factor authentication (2FA) or biometric verification, enhances security for online transactions. This additional layer of verification helps ensure that only legitimate customers can complete purchases, reducing the risk of fraud.
What Impact Does User Experience Have on Payment Processor Selection?
User experience significantly influences the selection of the best third-party payment processor due to factors such as ease of use, integration capabilities, and customer support.
- Ease of Use: A payment processor must provide a smooth and intuitive interface that simplifies transactions for both merchants and customers. If the system is complicated or cumbersome, it can lead to cart abandonment and frustration, ultimately impacting sales.
- Integration Capabilities: The ability to seamlessly integrate with existing platforms, such as e-commerce websites or accounting software, is crucial for maintaining workflow efficiency. A processor that offers robust APIs and plugins can enhance user experience by minimizing disruptions during the payment process.
- Customer Support: Reliable customer support is vital in resolving payment issues swiftly, which directly affects user satisfaction. Access to knowledgeable support teams can help businesses navigate challenges and ensure a smooth transaction experience for their customers.
- Security Features: Users are more likely to trust payment processors that prioritize security, offering features such as encryption and fraud detection. A secure transaction environment enhances user confidence, encouraging them to complete purchases without hesitation.
- Mobile Optimization: With an increasing number of transactions occurring on mobile devices, a payment processor must be optimized for mobile use. A poor mobile experience can deter users, making it essential for processors to ensure that their services are responsive and user-friendly across all devices.
Which Are the Best Third Party Payment Processors Available Today?
The best third-party payment processors available today offer various features, security measures, and pricing structures to accommodate different business needs.
- PayPal: One of the most widely recognized payment processors, PayPal offers easy integration and a user-friendly interface.
- Stripe: Known for its robust API and customization options, Stripe is favored by tech-savvy businesses looking for a tailored payment solution.
- Square: Square provides a comprehensive suite of payment solutions, making it ideal for small businesses and retailers with its point-of-sale systems.
- Authorize.Net: A long-standing player in the payment processing space, Authorize.Net is known for its reliability and extensive fraud detection tools.
- Adyen: Catering to larger enterprises, Adyen supports a wide range of payment methods globally and offers advanced analytics features.
PayPal: This platform allows businesses to accept payments via credit and debit cards, as well as PayPal accounts. It stands out for its ease of use, no monthly fees, and quick setup, making it accessible for entrepreneurs and small businesses.
Stripe: Stripe is designed for online businesses and offers extensive customization through its API. It supports various payment methods, including mobile wallets and subscriptions, and provides advanced reporting and analytics tools to track sales performance.
Square: Square is not only a payment processor but also provides hardware for point-of-sale transactions, making it a great option for brick-and-mortar stores. Its transparent pricing and free point-of-sale software make it easy for small businesses to manage in-person and online sales.
Authorize.Net: This processor is known for its strong security features, including fraud detection tools and secure customer data storage. It offers various payment options and is particularly popular among eCommerce businesses requiring reliable transaction processing.
Adyen: Adyen is tailored for larger businesses that operate globally and need a unified payment solution. It offers support for multiple currencies and payment methods, along with detailed reporting capabilities that help businesses optimize their payment strategies.
What Advantages Does PayPal Offer for Businesses?
PayPal offers several advantages for businesses looking for a reliable third-party payment processor:
- Wide Acceptance: PayPal is recognized globally, allowing businesses to reach a diverse customer base. With millions of users, customers are more likely to complete a purchase if they see PayPal as a payment option.
- Security Features: PayPal provides robust security measures, including encryption and fraud detection, which protect both businesses and customers. This assurance can enhance customer trust and lead to higher conversion rates.
- Easy Integration: PayPal can be seamlessly integrated into various e-commerce platforms and websites. This ease of setup allows businesses to start processing payments quickly without extensive technical knowledge.
- Mobile Compatibility: With a significant increase in mobile shopping, PayPal offers a mobile-friendly payment solution that enables customers to make purchases from their smartphones easily. This convenience can lead to increased sales and customer satisfaction.
- Flexible Payment Options: PayPal supports various payment methods, including credit/debit cards and bank transfers, giving customers the flexibility to choose their preferred way to pay. This versatility can improve the overall shopping experience and reduce cart abandonment rates.
- Instant Transactions: Payments made through PayPal are processed instantly, allowing businesses to access funds quickly. This rapid transaction capability can improve cash flow and help manage day-to-day operations more effectively.
- Customer Support: PayPal offers dedicated customer support to businesses, helping resolve issues promptly. This assistance can enhance the overall user experience and maintain smooth operations.
How Does Stripe Compare to Other Payment Processors?
| Feature | Stripe | Competitor A | Competitor B |
|---|---|---|---|
| Transaction Fees | 2.9% + 30¢ per transaction – Competitive rates for online payments. | 3.5% + 15¢ per transaction – Higher fees for credit card transactions. | 2.7% + 25¢ per transaction – Slightly lower fees than Competitor A. |
| Payment Methods | Accepts credit cards, debit cards, and various digital wallets. | Primarily credit and debit cards, limited wallet support. | Supports credit cards and PayPal but lacks other wallets. |
| Integration | Easy API integration with various platforms and languages. | Widely integrable, but setup can be complex. | Simple integration, but fewer customization options. |
| Customer Support | 24/7 support via chat and email, extensive documentation. | Limited support hours, primarily email-based. | Phone and email support during business hours only. |
| Mobile Payment Support | Supports mobile payments through various SDKs. | Limited mobile payment options. | Supports mobile payments, but fewer options. |
| Chargeback Fees | $15 per chargeback. | $20 per chargeback. | $25 per chargeback. |
| Payout Time | 1-2 business days for standard payouts. | 3-5 business days for standard payouts. | 1 business day for faster payouts. |
| International Support | Available in over 40 countries with multi-currency support. | Limited to specific countries, no multi-currency support. | Available in several countries, but high conversion fees. |
| User Experience | Intuitive dashboard, user-friendly interface. | Functional but less intuitive interface. | Very simple interface, but lacks advanced features. |
What Are the Typical Fees Associated with Different Third Party Payment Processors?
The typical fees associated with different third-party payment processors can vary significantly based on the service provider and the specific features offered.
- Transaction Fees: Most payment processors charge a fee for each transaction processed, usually a percentage of the sale amount plus a fixed fee. For example, a common structure might be 2.9% + $0.30 per transaction, which can add up for high-volume businesses.
- Monthly Fees: Some processors impose a monthly fee that covers account maintenance and access to their services. This fee can range from $10 to $50 or more, depending on the features provided, such as advanced reporting or fraud protection.
- Chargeback Fees: If a customer disputes a transaction and initiates a chargeback, processors may charge a fee to handle the dispute, which typically ranges from $15 to $30. These fees can accumulate quickly, especially for businesses with high return rates or customer disputes.
- Setup Fees: Certain payment processors may charge a one-time setup fee to establish your merchant account. This fee can vary widely, from nothing at all to several hundred dollars, depending on the complexity of the setup and the services included.
- Cross-border Fees: If you accept payments from international customers, some processors charge additional fees for currency conversion or cross-border transactions. These fees can be a percentage of the transaction or a flat fee, impacting overall cost-effectiveness for global sales.
- Additional Service Fees: Some payment processors offer optional services, such as advanced analytics, subscription billing, or enhanced security features, which can come with their own set of fees. Businesses should evaluate whether these additional costs align with their needs and budget.
How Can You Effectively Integrate a Third Party Payment Processor into Your Business Operations?
To effectively integrate a third-party payment processor into your business operations, you should consider several key factors:
- Research Payment Processors: Evaluate various third-party payment processors to find the best fit for your business needs.
- Assess Fees and Costs: Understand the fee structure associated with different payment processors to ensure they align with your budget.
- Integration Compatibility: Ensure that the chosen payment processor can seamlessly integrate with your existing systems and platforms.
- Security Measures: Prioritize payment processors that offer robust security features to protect customer data and reduce fraud risks.
- Customer Support: Look for payment processors that provide reliable customer support to assist with any technical issues that may arise.
- Testing and Launching: Conduct thorough testing of the payment processing system before going live to ensure a smooth customer experience.
Research Payment Processors: To find the best third-party payment processor, it’s crucial to assess different options available in the market. Review their features, usability, and reputation among other businesses to determine which processor aligns with your operational goals.
Assess Fees and Costs: Each payment processor has its own fee structure, which can include transaction fees, monthly fees, and setup fees. Understanding these costs will help you avoid unexpected expenses and choose a processor that offers the best value for your business.
Integration Compatibility: Check if the payment processor can be integrated with your current e-commerce platform, accounting software, and other business tools. A smooth integration process will minimize disruptions and streamline your operations.
Security Measures: Security is paramount when handling financial transactions. Look for payment processors that are PCI DSS compliant and offer features such as encryption and tokenization to safeguard sensitive information.
Customer Support: Good customer support is essential for resolving issues promptly. Choose a payment processor that offers multiple support channels, such as phone, email, and live chat, to ensure you can get help when needed.
Testing and Launching: Before fully launching your payment processing system, conduct extensive testing to identify and fix any potential issues. This step is vital to ensure that your customers have a seamless and hassle-free payment experience.
Related Post: